

Cleo AI: Cash Advance & Money
by Cleo AI
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
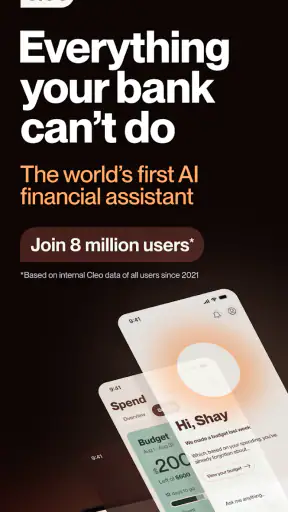
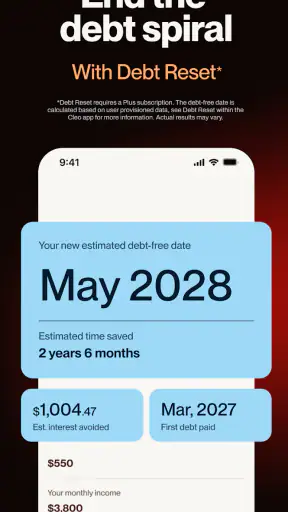
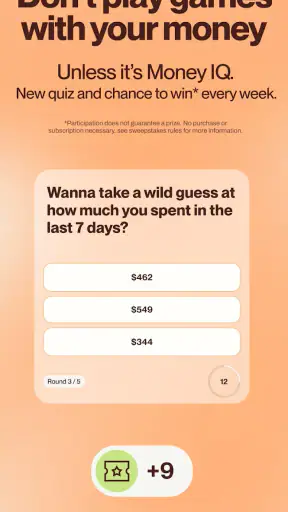
I approached Cleo AI as a money-management app rather than as a replacement for a bank. Its focus is practical: helping me look at spending, plan a budget, save, work on my credit, and handle tax-related tasks from one place. That combination makes it interesting for people who want financial guidance in a conversational format, especially if spreadsheets and traditional banking dashboards feel intimidating.
The app is developed by Cleo AI and is available as a free finance app for teenagers and older users. It has built a substantial audience, with over five million installs, a 4.7 average from around 142 thousand ratings, and roughly 40 thousand written reviews. Those figures suggest that the idea has connected with many people, although popularity alone does not tell me whether its approach will suit every financial situation.
How Cleo AI feels to use in everyday money management
I find Cleo AI most useful when I treat it as a prompt to make one thoughtful money decision, not as a place to resolve every financial question at once. A quick check-in can turn a vague worry about spending into a clearer next step, while still leaving room to verify the details that matter. That everyday rhythm is what shapes how I approach its tools in practice.
Readability and navigation for different levels of confidence
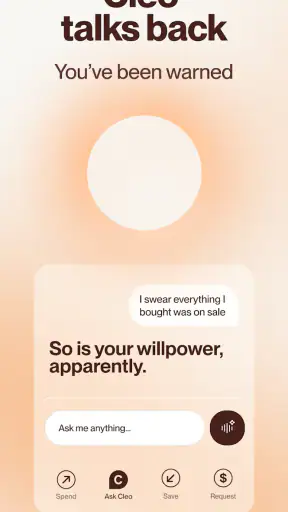
The strongest part of the experience is the attempt to make financial information feel less formal. Instead of presenting every decision as a dense report, Cleo AI is designed around a more conversational relationship with money. I found that approach useful when I wanted to ask a simple question, check my habits, or turn a vague goal such as “spend less this month” into something I could think about more clearly.
That conversational style can be especially helpful for someone opening a budgeting tool for the first time. Traditional finance apps often lead with account balances, categories, charts, and unfamiliar terms. Cleo AI puts more emphasis on plain-language interaction, which can reduce the mental effort required to understand where to begin. For users who are nervous about money, that softer entry point matters.
At the same time, conversational navigation is not automatically clearer for everyone. A person who prefers a fixed menu, predictable labels, and a complete overview may find a chat-led approach slower than a conventional budgeting dashboard. When I want to compare several spending categories quickly, a structured table or spreadsheet can still be more efficient. Cleo AI works best when I am willing to interact with the app step by step rather than expecting every detail to be visible at once.
One useful habit is to use the app for short, specific check-ins instead of trying to solve an entire financial life in a single session. I might review recent spending, decide what amount is safe to set aside, and then leave with one action. Breaking the process into smaller questions makes the conversational format easier to follow and reduces the chance of overlooking an important detail.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The wording is also important for people who struggle with financial vocabulary. Budgeting, credit, saving, and tax tasks can each involve terminology that creates unnecessary barriers. A plain explanation can help a new user understand the next step without first learning the language of personal finance. However, I would still verify any serious financial decision independently. Friendly wording makes information easier to approach, but it should not be mistaken for professional financial advice.
Motor and sensory considerations during regular use
For users with motor difficulties, a conversational workflow may be less demanding than repeatedly moving through complex spreadsheets or tightly packed banking screens. Fewer simultaneous choices can make it easier to focus on one task. Someone using a phone one-handed, relying on larger system text, or needing more time to complete an interaction may appreciate a less data-heavy starting point.
There is a trade-off, though. Any app that expects frequent typing, tapping, scrolling, or reading can become tiring for people with limited dexterity, tremors, fatigue, or pain. The practical experience will depend on the phone, operating-system settings, and the individual’s needs. I would not assume that a conversational interface removes all physical effort. Before committing to regular use, I would test whether the main actions remain comfortable with the device’s own accessibility settings enabled.
People with visual or cognitive differences may benefit from the app’s attempt to explain money in everyday language, but readability is more than vocabulary. Financial information can still be stressful when several figures, categories, or decisions appear together. I found it easier to use when I paused after each recommendation and considered whether it matched my real circumstances. That slower rhythm is worthwhile for anyone who needs extra processing time.
Users with hearing loss are less likely to be disadvantaged by a primarily text-based interaction than they might be in an audio-first service. Conversely, people who depend on spoken interaction may find a text-heavy money workflow less convenient. I would treat the app as a visual and conversational tool, not assume that it provides an equally comfortable experience through every input method, and check the phone’s built-in tools if reading or typing is difficult.
Situational access: when the app is most useful
Cleo AI makes the most sense during small gaps in a normal day. I can imagine using it after a grocery trip to understand whether an impulse purchase fits the month’s plan, or checking in before a bill-heavy week to avoid spending money that is already committed. This is different from sitting down for a full financial review. The app’s value is strongest when it helps turn a moment of uncertainty into a manageable next question.
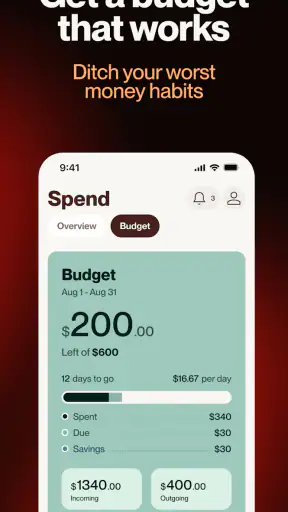
A realistic example would be someone paid near the beginning of the month who tends to spend freely during the first week. Rather than waiting until the balance feels unexpectedly low, that person could use the budgeting and saving tools to create a clearer boundary around discretionary spending. The important insight is not simply to set a target; it is to review the target after real expenses arrive. A budget that looks sensible before transport, food, and household costs appear may need adjustment afterward.
The saving side can also be useful for people who need encouragement more than complicated investment tools. A modest goal feels easier to approach when it is connected to a specific purpose, such as an upcoming expense or a buffer for an uneven month. I would avoid treating an automated saving suggestion as universally safe, though. Anyone with irregular income, overdraft risk, or urgent bills should protect essential cash flow before moving money toward a goal.
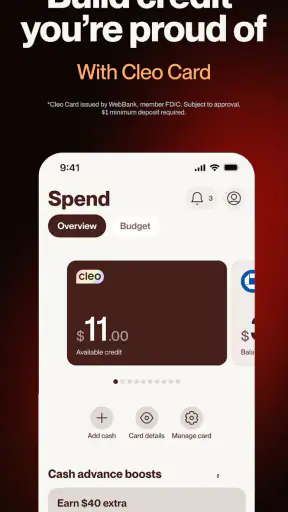
The credit-related tools may appeal to someone trying to understand and improve their credit habits, particularly if the subject feels confusing. The app can serve as a prompt to pay attention to credit rather than ignoring it. Still, credit improvement is gradual and depends on broader financial behavior. I would use Cleo AI as an organizing and educational aid, while checking important account information through the relevant lender or credit-reporting source.
The tax function gives the app a wider use case than a basic spending tracker. It may be attractive to someone who wants to keep money management and tax preparation in the same general environment. Even then, tax situations vary considerably. A straightforward return and a complicated return should not be treated as the same task, and anyone with unusual income, multiple jurisdictions, or uncertainty about a filing decision may be better served by a qualified tax professional.
Where Cleo AI compares well with usual alternatives
Compared with a spreadsheet, Cleo AI is more approachable for someone who does not enjoy building formulas, maintaining categories, or designing a tracking system from scratch. A spreadsheet gives me maximum control, but that control comes with ongoing work. Cleo AI is the better fit when I want guidance and momentum rather than a completely custom financial model.
Compared with a standard banking app, it appears more focused on behavior and planning than on simply showing transactions and balances. A bank app remains the place I would expect to handle core account activity, while Cleo AI is more useful as a layer for reflection, budgeting, saving, and credit awareness. Keeping those roles separate helps prevent confusion about where an important transaction or account decision should be managed.
Compared with a dedicated tax service, the broader scope is both an advantage and a limitation. Having tax-related help alongside budgeting can feel convenient, but a specialist tax product may be preferable when filing is the main priority. Likewise, a dedicated credit-monitoring service may offer a more focused experience for someone whose only goal is tracking credit-related information.
The app’s free price lowers the barrier to trying it, which is valuable for users who are cautious about adding another financial tool. I would still read any in-app terms carefully before accepting optional services or making a financial commitment. “Free” makes experimentation easier, but it does not remove the need to understand what a particular feature does.
Remaining barriers and points that deserve caution
The biggest barrier is not necessarily the interface; it is the emotional weight of financial information. Someone dealing with debt, unstable income, or missed payments may find any budgeting conversation uncomfortable. A friendly tone can make the first step easier, but it cannot remove the underlying problem. I would recommend using the app in short sessions and choosing one practical action rather than judging the entire financial situation at once.
Another limitation is the risk of overreliance. Because the experience is designed to feel approachable, users may accept a suggestion quickly without checking whether it fits their obligations. I would always compare proposed spending or saving decisions with upcoming bills, account balances, and income timing. This is particularly important for people whose finances change from week to week.
People who need extensive customization may also reach the app’s limits sooner than casual users. A detailed household budget can involve shared expenses, irregular earnings, reimbursements, business costs, and special categories. A conventional budgeting system may provide finer control in those cases. Cleo AI is more compelling for guided personal money management than for building an accountant-style record.
Privacy and trust are also central considerations for any finance app. I would take time to understand the connection process, review what I am comfortable sharing, and avoid linking accounts casually just to explore a feature. This is not a criticism unique to Cleo AI; it is a sensible standard for every service that works with personal financial information.
For teenagers, the content rating of Teen makes the app relevant to a younger audience, but age alone does not guarantee financial readiness. A young user may need help understanding budgets, saving decisions, credit concepts, and tax responsibilities. I would encourage a parent, guardian, or trusted adult to be involved where appropriate, especially if the user is making decisions that affect real household finances.
Support for different abilities and contexts
What I appreciate most is the app’s potential to lower the intimidation factor. Someone who finds financial tables difficult to interpret may be more willing to start with a conversation. Someone with limited time can use a short check-in instead of preparing a full monthly report. Someone who has repeatedly abandoned spreadsheets may benefit from a guided routine that keeps attention on one decision at a time.
That inclusiveness has boundaries. The app cannot be assumed to meet every accessibility need, and the experience may vary depending on device settings, input preferences, reading comfort, and the complexity of a person’s finances. I would test the core workflow early: open the budgeting area, review a spending question, examine the saving process, and see whether the text and interaction pace feel manageable.
A practical accessibility strategy is to pair the app with the phone’s own display and interaction tools. Larger text, stronger contrast, screen magnification, voice input, and reduced motion can make mobile finance tasks more comfortable when those options are available on the device. I would also avoid using the app while rushed, distracted, or in a noisy public place. Financial decisions deserve enough attention to catch a mistaken category or an unrealistic goal.
The current version is 3.67.0, and the app supports operating systems from version 10 onward. That makes device compatibility an important first check for anyone using an older phone. If a user cannot keep the operating system current or relies on an older handset for accessibility reasons, confirming compatibility before building a routine around the app would be sensible.
Who should try it, and who should choose something else?
I would recommend Cleo AI to a person who wants a friendlier way to begin budgeting, needs encouragement to save, or wants one place to think about spending and credit. It is particularly appealing to users who dislike spreadsheets and find traditional banking interfaces too passive. The free entry point also makes it reasonable to test without immediately paying for a specialist service.
I would be more cautious about recommending it as the only financial tool. People with complex tax affairs, detailed household accounting needs, severe financial distress, or a strong preference for manual control may be better served by a specialist app, a spreadsheet, a bank’s own tools, or professional advice. The right choice depends on whether the user needs guidance or precision. Cleo AI leans toward guidance.
I would also skip it if conversational interaction feels irritating rather than helpful. Some people want a clear ledger, exportable records, and direct controls with minimal personality. For them, a conventional budgeting application may be less distracting and easier to audit. An app should fit the way someone thinks, not force them into a style that feels unnatural.
My inclusive verdict
Cleo AI is a thoughtful finance app for making money conversations less intimidating. Its combination of budgeting, saving, credit support, and tax-related functionality gives it more range than a simple expense tracker, while its conversational approach can help people who struggle with formal financial tools. I found its greatest strength in encouraging small, understandable decisions rather than demanding a perfect financial system from the beginning.
Its limitations are just as important. A friendly interface does not replace careful checking, specialist tax support, or a detailed ledger when those are necessary. Accessibility will depend on the user’s device, preferences, and financial situation, so I would test the main workflow instead of assuming it will suit everyone equally.
My recommendation is to try it as a supportive layer for everyday money awareness. Use it to establish a routine, question spending habits, and create realistic saving steps, but keep important records and decisions grounded in verified account information. For the right user, the most valuable feature is not a single financial tool but the lower-friction path into taking control. That makes it worth considering, provided its conversational guidance matches the way you prefer to manage money.
Pros
- User-friendly interface for easy navigation.
- Quick setup with minimal personal info needed.
- Real-time spending insights and alerts.
- AI-driven personalized financial advice.
- Secure connection with bank-grade encryption.
Cons
- Limited to certain countries and currencies.
- Occasional syncing issues with bank accounts.
- Cash advance feature may have hidden fees.
- AI advice may not suit all financial situations.
- Requires constant internet connection to function.
FAQs for Cleo AI: Cash Advance & Money
What is Cleo AI: Cash Advance & Money, and how does it work?
Cleo AI is a financial assistant app designed to help users manage their money more effectively. It offers features like cash advances, budgeting tools, and spending insights. By linking your bank account, Cleo provides personalized financial advice, tracks your spending habits, and helps you save money with its smart AI-driven recommendations.
Is Cleo AI safe to use with my banking information?
Yes, Cleo AI uses bank-grade security measures to protect your data. The app employs encryption and secure protocols to ensure that your information remains confidential and safe. Cleo does not store your login credentials, and it only reads your transaction history to provide insights, without having the ability to make changes or transactions.
What are the main features of Cleo AI?
Cleo AI offers a range of features including budgeting tools, spending analysis, and cash advances. Users can set savings goals, receive insights on their spending patterns, and access a chat interface for financial advice. The app also provides alerts and reminders to help users stay on track with their financial objectives.
Are there any fees associated with using Cleo AI?
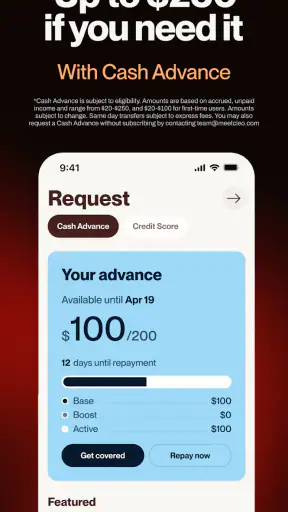
Cleo AI offers both free and premium subscription plans. The free version provides basic features such as budgeting and spending insights. The Cleo Plus plan, which requires a monthly fee, offers additional benefits like higher cash advance limits and more personalized financial advice. Users can choose the plan that best suits their needs.
How does Cleo AI’s cash advance feature work?
Cleo AI offers a cash advance feature that allows users to borrow small amounts of money quickly. This service is available to eligible users and can be a helpful way to cover unexpected expenses. The amount you can borrow and the terms will depend on your financial profile, and repayments are typically scheduled with your next paycheck.

Cleo AI: Cash Advance & Money
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via team@meetcleo.com, visit https://meetcleo.com, or review their https://www.meetcleo.com/privacy.










